vc.web.local

The concession's advance sustainability scopes are one of the prime reasons that locked the deal for ADNOC. (Image source: Adobe Stock)

In its first strategic investment in Mozambique, ADNOC has acquired 10% of Galp’s interest in the Area 4 concession of the Rovuma basin in Mozambique

The acquisition will allow ADNOC a share of the liquefied natural gas (LNG) produced from the concession.

With the operational Coral South Floating LNG (FLNG) facility, the planned Coral North FLNG development and the planned Rovuma LNG onshore facilities, the concession has a combined production capacity of more than 25 mn tonnes per annum. It is one of the world’s largest gas discoveries in 15 years. 

A one-of-a-kind facility in Africa, the Coral South development is currently in operation, with a production capacity of up to 3.5 mtpa of LNG. Once up and running, the Coral North development is capable of adding another 3.5 mtpa of LNG to that. It will have a FLNG facility to process and liquefy natural gas for export. 

The Coral south development is already yeilding vegetable oil to serve as feedstock in Eni's biorefineries. 

The modular, electric-drive design of the 18-mtpa Rovuma Onshore LNG development is capable of challenging industry standards when it comes to carbon intensity reduction from LNG production. 

The concession's advance sustainability scopes are one of the prime reasons that locked the deal for ADNOC, which aims to achieve a just transition-driven net zero by 2045. 

Integrated global gas business 

Musabbeh Al Kaabi, ADNOC executive director for low carbon solutions and international growth, said, “For over fifty years, ADNOC has been a reliable and responsible global provider of LNG and we are building on this role with this landmark investment in the world-class Rovuma supergiant gas basin in Mozambique as we deliver on our international growth strategy. Natural gas plays an important role to meet growing global demand with lower emissions compared to other fossil fuels and this acquisition supports our efforts to build an integrated global gas business to ensure we continue providing a secure, reliable and responsible supply of natural gas.”


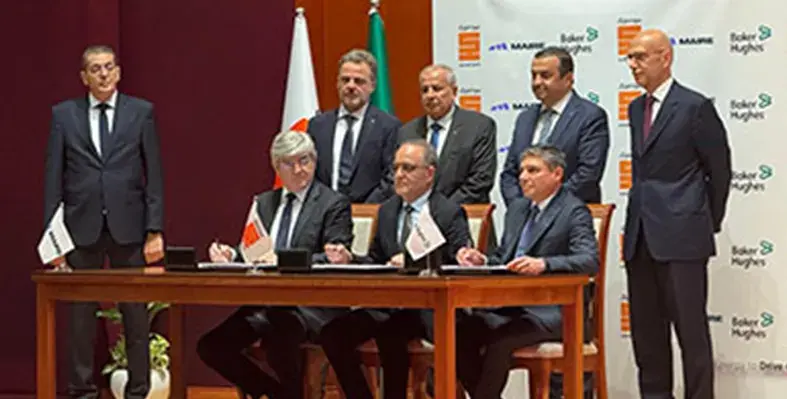
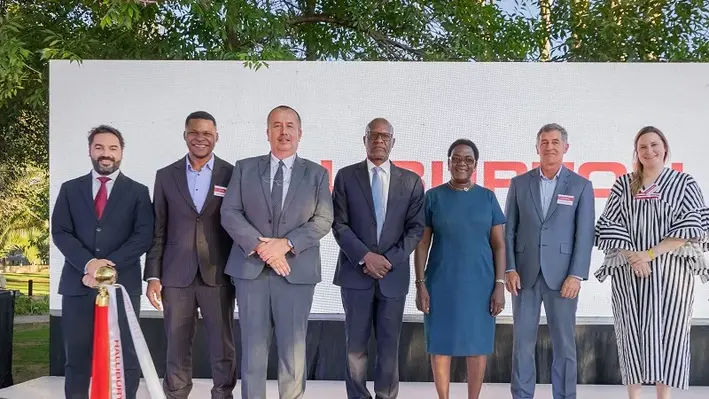
The signing ceremony included the CEOs of Baker Hughes, SONATRACH and MAIRE, and the Minister of Energy and Mines. (Image source: Baker Hughes)

In an effort to boost production from Hassi R’Mel gas field 550 km south of Algiers, SONATRACH has signed a contract with Baker Hughes

The energy technology company will supply 20 compression trains based on Frame 5 gas turbine and BCL compressor technology will be installed across three gas boosting stations within the Hassi R’ Mel gas field. 

This comes as part of the Mattei Plan, a broader strategic collaboration across industries between Algeria and Italy. Italy has assured financial support for Algeria's gas production, which is the European nation's biggest single source of import. 

In 2023, Bloomberg NEF recognised Algeria as the second-largest gas supplier to Europe. The country has introduced multiple gas boosting stations to hold its title on the global energy market, while embracing natural gas as its prime energy source for socio-economic development. In June last year, TotalEnergies signed contract with SONATRACH to develop gas resources in the north-east Timimoun region. The oil major has also extended its LNG contract with SONATRACH till 2025 to access 2 mn tonnes of LNG for France and Europe.  

The largest gas field in Algeria, Hassi R’ Mel is equipped to not just meet domestic demands but also serves as key source of energy supply for Europe. At more than 20 trillion cu/m, shale gas is a lucrative investment opportunity for Algeria which falls under SONATRACH's long-term development plans as the company's vice president for planning and strategy, Rachid Zerdani noted last year. 

Baker Hughes responsibilities on Hassi R’ Mel will include boosting and stabilising the pressure of natural gas to increase production at site. Its facility in Italy will be the base for all project activity from compressor trains packaging and manufacturing to trains testing. This comes as a sub-contract of an order awarded to a consortium between Baker Hughes and technology and engineering group MAIRE-subsidiary Tecnimont. 

Reliable energy source for Europe

“We have long believed that it is critical to increase gas within the overall global energy mix to help achieve a lower-carbon economy. This project helps to solve for energy producers’ multi-faceted challenge of driving sustainable energy development as energy demand increases. We are proud to support such a critical energy project in partnership with Tecnimont,” said Lorenzo Simonelli, chairman and CEO of Baker Hughes. 

“Today’s announcement marks a notable milestone in our historical collaboration with SONATRACH for key energy projects in Algeria that have played a crucial role in supplying reliable energy to Europe,” said Simonelli on the occasion of contract signing, which also included Rachid Hachichi, CEO, SONATRACH; Alessandro Bernini, CEO, MAIRE, and the Minister of Energy & Mines, Mohamed Arkab.


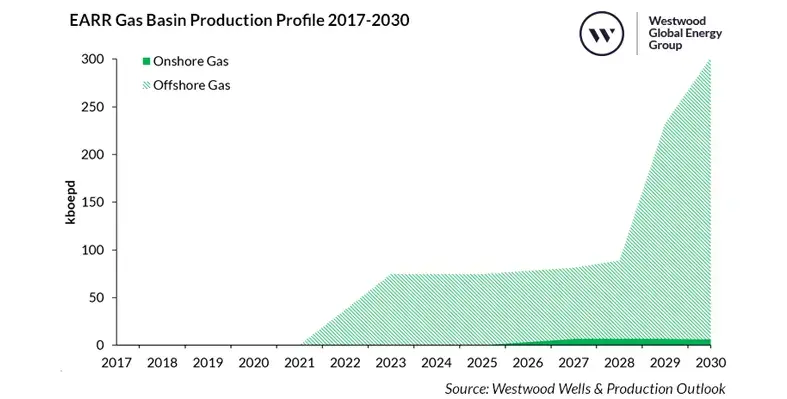
There is a potential for an uptick in E&A drilling activity. (Image source: Westwood)

Mozambique can still lead production and drilling in the East African Ruvuma-Rufiji (EARR) Gas Basin through to 2030, if the government continues to take strides to guarantee rapid progression of projects off Cabo Delegado province, writes Michela Francisco, analyst - onshore energy services, Westwood Global Energy Group

According to bp's 2024 Energy Outlook, global liquefied natural gas (LNG) traded volumes are forecast to grow 43% by 2030 from the 543 bn cu/m recorded in 2022

In recent years, LNG exports have been dominated by the United States, Australia and Qatar, which, according to the Energy Information Administration (EIA), held a combined LNG export capacity of approximately 257 mmtpa in 2023 (60% of total global LNG capacity). By 2030, Qatar and the US are projected to add approximately 150 mmtpa in LNG feedstock, securing the top two positions in global LNG export capacity. New additions are anticipated to stem from LNG facilities currently under construction in the US (84.1 mmtpa) and expansion phases of QatarEnergy’s North Field (65mmtpa). Despite this, there is still an appetite for additional LNG supply, given current demand expectations, making the business case for developing long-stalled gas projects from frontier areas stronger.

Mozambique and Tanzania, which house the EARR Gas Basin, could potentially be major beneficiaries of this projected demand, given abundant gas reserves (165.7 trillion cu/ft) and the basin's proximity to South-Asian import markets. However, the burning question remains – how soon can the world expect the EARR Gas Basin to roar amid an increasingly thirsty LNG demand environment?

It is pertinent to state that the EARR Gas Basin has failed to live up to its full potential due to a series of endemic bottlenecks faced in the host countries. In Tanzania, the US$40bn Tanzania LNG project, which aims to receive gas feedstock from six fields across Blocks 1 and 4 (Shell) and Block 2 (Equinor), has been subject to extensive delays due to protracted negotiations rooted in unattractive fiscal terms due to high domestic supply obligations.

The story behind undeveloped gas reserves is quite different for the reserves offshore Mozambique, with the main culprit being the Islamist insurgency in Cabo Delgado province. The conflict has led to delays in final investment decisions (FIDs) and project start-ups, given declarations of force majeure for key projects. An example is TotalEnergies’ enforcing force majeure on the 13 mmtpa Mozambique LNG project, hereby delaying production start from the operator's Golfinho-Atum field into 2028, nine years post sanction.

On a similar note, ExxonMobil's Rovuma LNG project also felt the knock-on effect following the declaration of force majeure by TotalEnergies, given that it plans to share some facilities belonging to the Mozambique LNG project. ExxonMobil, however, seized this as an opportunity to cut costs by heavily reconfiguring the design plan from its initial two-train 15.2 mmtpa stick-build facility to an 18 mmtpa facility now being constructed using a modular approach whilst putting some emphasis on mitigating greenhouse gas emissions from the project. To date, ExxonMobil has launched tenders for a front-end engineering and design (FEED) contract and an engineering, procurement, construction and installation (EPCI) option for the subsea-to-shore gas gathering facilities.

Another factor contributing to the untimely development of resources in Mozambique is complicated project economics. TotalEnergies highlighted this in 2023 when it reported that supply chain inflationary pressures further complicated the resumption of the US$20bn Mozambique LNG project. However, there have been signs of positive developments given that TotalEnergies communicated in the company’s April 2024 earnings call that contractors have agreed to reverse contract inflation plans; thus, this is no longer an obstacle to the project’s sanctioning decision.earr gas basin

Despite these challenges, the Basin's inaugural project, Eni's 75,000 boepd Coral South floating liquified natural gas (FLNG) project, came onstream in 2022, signalling that complex, multi-billion-dollar developments could work offshore Mozambique. Output in Mozambique is forecast to remain stable at around 75,000 boepd until 2027 before growing to a peak of 295,000 boepd by 2030, up 296%, driven by TotalEnergies’ Golfinho-Atum and Eni's Coral Phase II fields.

Additionally, Tanzania's inaugural field in the Basin should come onstream in 2026 from Aminex's 7000 boepd Ntorya onshore gas field, boosting total output across the Basin to a peak of approximately 302,000 boepd by 2030, up 305% on 2023. Although there are positive signs for production, the spectre of delays that have been haunting projects remains strong, potentially diluting the positive picture prior to 2030, especially since only one of the three projects expected onstream by 2030 has passed sanctioning (TotalEnergies’ Golfinho-Atum). 

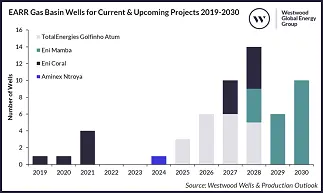
Drilling activity across both countries has been negligible, averaging one well per annum over the 2019-2024 period. Activity is anticipated to liven up over the forecast, driven by approximately 50 wells to be drilled to support upcoming LNG projects in Mozambican deepwater. Of these, 27 subsea trees have already been awarded between 2017 and 2019 for Eni’s Coral South and TotalEnergies’ Golfinho-Atum fields. 30 additional subsea trees are forecast to be awarded, with six awards anticipated for Eni’s Coral North field, scheduled to reach FID before the end of 2024. Onshore drilling activity will remain negligible, with only Aminex’s Chikumbi-1 exploration well set to be spud in 2024, the only onshore E&A well spud in the basin since 2016.

Post 2030, the outlook from the EARR Basin could be more promising, given continued interest from international energy companies (IECs), as well as licencing rounds and concession award announcements made across both countries since 2023. Although projects are few and far between in Tanzania, Shell and Equinor proposed a US$42bn LNG project from three deepwater blocks in March 2023, and this was later followed by CNOOC’s expression of interest in developing a FLNG deepwater project in blocks 4/1B and 4/1C in June 2023. From a regulatory standpoint, the current administration has increased optimism, given ongoing negotiation on fiscal terms with joint venture companies; however, nothing has materialised thus far.

Additionally, it is noteworthy to highlight the potential for an uptick in E&A drilling activity beyond Westwood’s current forecasts. This is due to the semi-autonomous Government of Zanzibar, off-Tanzania, launching its inaugural five-year licensing round in March of 2024, inviting IECs to explore eight offshore blocks.

earr gas basinsE&A drilling could also occur in Mozambique, given that the National Hydrocarbon Company approved a concession contract for oil exploration and production in the Angoche A6-C Area in July 2024. However, Westwood is bearish on these progressing into any E&A drilling activity before the second half of the forecast.
When dissecting current developments in the EARR Basin, it is evident that by the onset of the next decade, the Basin could contribute about 295,000 boepd of gas to meet global LNG demand. Westwood anticipates that Mozambique will continue to lead production and drilling in the EARR Basin through to 2030. However, it remains crucial for the Mozambican government to continue to take strides towards eradicating the insurgency to guarantee rapid progression of projects off Cabo Delegado province, which are currently mainly in the FEED stage.

Contrarily, on the Tanzanian side of the Basin, the portrait is more promising than in the hindcast, albeit there is still a need to focus on improving fiscal terms to attract more near-term investment and ensure that current interest from IECs is maintained. Overall, Westwood believes that by 2030, the EARR Gas Basin might start to live up to its potential as projects finally move from potential to reality.

APT has a gas sales agreement with TPDC. (Image source: Adobe Stock)

ARA Petroleum Tanzania and its development partner Aminex Plc have received a 25-year development licence over the Ntorya Gas discovery in Tanzania from the Deputy Prime Minister and Minister for Energy of Tanzania, Doto Mashaka Biteko

“We were honoured to receive this licence from Deputy Prime Minister Doto Biteko at such a prestigious event. This ceremony marked a significant milestone in our commitment to harness Tanzania’s gas resources for the benefit of its people. Our ambition for this serious endeavour is that it results in boosting economic development, alleviating energy poverty and supporting the country’s energy transition,” said Erhan Saygi, general manager, ARA Petroleum Tanzania, commenting on the handover ceremony that took place in Mtwara.

APT has acquired land for the installation of upstream processing facilities, and the Chikumbi-1 appraisal well location, while expanding an adjacent site to accommodate the construction of a camp and storage yard. It is also putting into place the logistics necessary to conduct the subsurface work that will lead to first gas production. This includes conducting a well-test on Ntorya-2 and converting it to a producing well, drilling the Chikumbi-1 appraisal well with a view to converting it to a producing well and carrying out a well workover at Ntorya-1, before turning it into a producing well. 

The company is aiming the completion of pipeline placement from Ntorya to Madimba by early next year, working in line with the Tanzanian government's ambitions to enable gas delivery for electricity generation in the Mtwara region. 

According to a Gas Sales Agreement signed with the Tanzanian Petroleum Development Corporation (TPDC) earlier this year, APT expects an initial yield of 40 to 60 mn st cu/ft a day in the first year, gradually boosting production to 140 mn st cu/ft over the next few years. 

This estimate is backed by strikingly positive 3D seismic datasets from the region, indicating significant potential gas volumes in other untested structures over the wider licence area. To emphasise just how significant the potential gas volumes might be, Charles Santos, the executive chairman of Aminex, has said that the Ntorya accumulation can become the largest onshore gas discovery in East Africa. 

This, however, will require investment in a phased development of the Ntorya gas field and the maturing of domestic industries as gas offtakers, such as fertiliser, cement and plastics production plants, vehicle CNG stations, domestic LPG suppliers and additional gas-fired power stations for industrial and residential use.

Ntorya gas hub

“We are excited about further exploration and appraisal work in this area as we consider it to hold truly enormous volumes of gas. We believe this could be game-changing for Tanzania’s energy security, for Mtwara’s industrial development and for Tanzanians’ prosperity. We look forward to building strong partnerships with local businesses and entrepreneurs to share knowledge, impart expertise and build a home-grown industry around a Ntorya gas hub,” said Saygi.

APT has been actively involved in the Ruvuma Asset since 2020, before its interests in the region accumulated to 75% post acquisition from Scirocco Energy last year. The remaining 25% interest in the Ruvuma Asset is held by Aminex.


Top Stories

Grid List

VAALCO Energy has completed its Phase 3 offshore drilling programme in Gabon, bringing the ETSEM-3H development well into production and demobilising the Borr Norve drilling rig from the SE Etame platform

The company has also commenced drilling activities under the Baobab Phase 5 campaign offshore Côte d’Ivoire

At the SE Etame field in Gabon, the ETSEM-3H well was drilled and completed in an attic location, targeting 300 metres of net pay in high-quality Gamba reservoir sands along its lateral wellbore. The well achieved a stabilised initial production rate of approximately 2,000 gross barrels of oil per day (BOPD), equivalent to 1,140 BOPD net to VAALCO.

With ETSEM-3H completed, the Phase 3 drilling programme has concluded, and the Borr Norve rig has been removed from the field.

Offshore Côte d’Ivoire, work has begun on the Baobab Phase 5 drilling programme, with the operator batch-setting the top-hole sections of the planned wells. Once the top-hole sections have been drilled across the programme, the wells will be completed and brought into production sequentially.

The campaign comprises four production wells, three water-injection wells and two workovers. VAALCO expects the first new producer to come online towards the end of 2026, with the programme anticipated to support significant production growth in 2027.

George Maxwell, VAALCO’s Chief Executive Officer, commented, “We are pleased with the results of the ETSEM-3H development well, which was landed in an attic location within the SE Etame field, and is now on production at about 2,000 gross BOPD (1,140 BOPD net to Vaalco). This represents the final well in our successful Phase 3 drilling campaign, and the drilling rig has now been demobilized from the field. In Côte d’Ivoire, following the successful re-start of the Baobab field during the second quarter, we have now commenced the Phase 5 drilling campaign with batch-setting the top-hole sections of the new wells. The current plan for the Phase 5 drilling campaign consists of four producers, three water injectors and two workovers. We expect to have the first new producer online near the end of the year, with meaningful production increases expected in 2027. Our continued success and organic project pipeline support Vaalco’s strategic focus on growing production, reserves and value for our shareholders.”

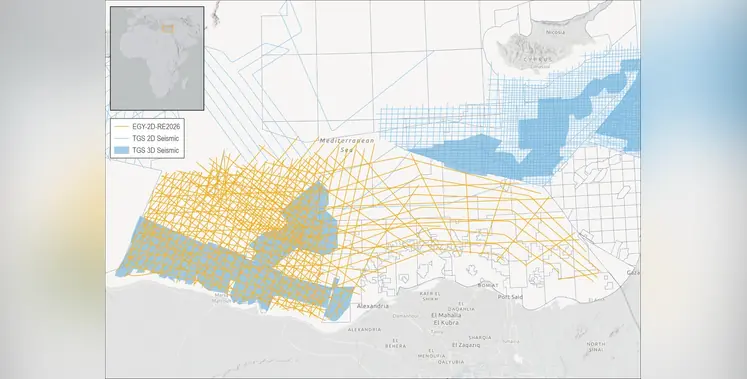
The survey will span across 34,000 kms offshore Egypt. (Image source: TGS)

Geology & Geophysics

Energy data and intelligence provider, TGS, has partnered with Egyptian Natural Gas Holding Company (EGAS), to initiate a large-scale 2D seismic reimaging campaign, the EGY-2DRE2026 project 

The survey will span across 34,000 kms offshore Egypt, which will be further integrated to the GeoStreamer 2016, 2018 and 2023 surveys. The compilation will comprise other available conventional 2D data as well, building single and consistent regional framework for interested operators to refer to across the offshore basins. The vast and insightful dataset will be fed into an advanced velocity model building and pre-stack depth migration workflow, including TGS' proprietary DM-eFWI technology, to generate credible images of pre-, intra- and post-Messinian salt intervals in high definition. 

The reimaged dataset that spans offshore Nile Delta, Herodotus Basin, and wider Eastern Mediterranean Basin will support clients to better resolve these intervals, giving a sharper, basin-wide structural framework to support prospect identification and maturation. This will play a significant role in decision making for operators to channelise exploration budgets in the right direction ahead of upcoming licensing rounds.

To support resource development, TGS has lately been taking up region-specific projects in Africa that aligns with a rising global demand for basin-wide reimaging and data integration across frontier and mature basins globally.

Final products for a priority subset of 2D lines are scheduled for delivery in Q2 2027, with the remaining full project scheduled for completion in Q1 2028.

"EGY-2DRE2026 will give our customers a modern, regionally consistent view of a basin that has historically been difficult to image beneath its complex Messinian section," said David Hajovsky, Executive Vice President, Multi-Client at TGS. "By combining our latest imaging technology with the depth and breadth of our existing coverage, we're able to de-risk exploration decisions and support our customers as they evaluate future opportunities in this highly prospective part of the Egyptian offshore."

The project is supported by industry funding.

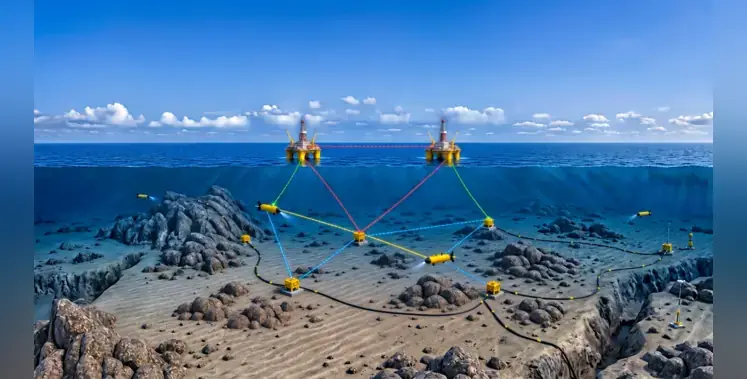
The new standard represents an important step towards optical modem interoperability for subsea systems. (Image source: SWiG)

Technology

Oil and gas industry network Subsea Wireless Group (SWiG) has released a new industry specification for free-space optical communications, providing a common protocol for modems from different manufacturers

SWiGoptical Level 1 defines a simple protocol to satisfy interoperability and interchangeability requirements for subsea free-space optical communication devices. It supports applications including, but not limited to, process control, equipment and process monitoring, diagnostics and maintenance, and data exchange and harvesting across autonomous underwater vehicles (AUVs) and other connected subsea systems.

Systems working together

SWiG, a joint industry project (JIP) managed by OTM Networks (part of R&D consultancy Sagentia Innovation), was established to enable vehicles, infrastructure and equipment from different suppliers to work together seamlessly. It has 27 members representing all parts of the supply chain, from major energy operators to subsea service providers and integrators to specialist instrumentation companies. Its objectives include:

• Promote interoperability between users of subsea wireless communications.
• Raise industry awareness and acceptance of subsea wireless communications.
• Identify areas (within subsea wireless communications) where open standards are needed, and develop them.
• Encourage the integration of subsea wireless communication technologies.
• Share best practices across the industry.
• Promote knowledge transfer across the industry.

Shreekant Mehta, senior vice president, Energy Sector at Sagentia Innovation, said SWiGoptical Level 1 represents an important step towards optical modem interoperability for subsea systems.

“SWiG’s goal is to create a common subsea ecosystem where devices from different manufacturers interact seamlessly,” Mehta explained. “As subsea communication technologies continue to mature, a collaborative approach to developing open standards supports cost management and provides a common framework, reducing deployment risk, simplifying integration and supporting scalability. Achieving interoperability across subsea operations is essential if the industry is to realise the full benefits of autonomy.”

The new specification builds on the earlier SWiGacoustic standard and is the latest in a family of complementary SWiG standards that also cover radio frequency (RF), inductive data and power and hybrid communications. SWiGoptical Level 1 is now available to the wider industry, with Level 2 and Level 3 specifications for higher-performance protocols already under development.

First gas from NT-1 and NT-2 is targeted for December.

Gas

The giant Ntorya gas field development in Tanzania is anticipated to deliver vital domestic energy supplies, alleviate local energy poverty, and drive long-term industrial and economic growth for the country

Tanzanian government authorities have recognised the urgency of the project's advancement and to make sure there is no delay, an optimised timetable has been established in consultation with the joint venture partners involved in the field's development. Designed with an aim to achieve first gas production by December, the packed schedule includes critical well workovers, testing, and accelerated drilling. Fully funded field operations and pipeline infrastructure integration will prepare the site for production generation.

Aminex has reached an agreement on the sequencing and implementation of the Ntorya gas development following a meeting convened by the Tanzanian Ministry of Energy

Key stakeholders convene

Representatives of the Ministry of Energy, the Petroleum Upstream Regulatory Authority (PURA), the Tanzania Petroleum Development Corporation (TPDC), ARA Petroleum Tanzania Limited (APT), the operator of the Ruvuma PSA, and Aminex's wholly owned subsidiary, Ndovu Resources Limited (Ndovu) were present at the meeting.

While the government did not approve the operator's proposal to extend and delay the project timetable, it did confirm a revised implementation schedule with all the parties involved. This schedule comprises workover of the Ntorya-1 well (NT-1) in October, the testing of the Ntorya-2 well (NT-2) in November and the drilling of a newly planned NT-Central well (NT-C) in December.

First gas from NT-1 and NT-2 is targeted for December. Drilling of the Chikumbi-1 well (CH-1) is to proceed after NT-C is drilled. Following the change of management at ARA Petroleum LLC and a technical reappraisal of the Ntorya project, APT had proposed bringing forward NT-C, previously planned as a development well for a later phase of field development, in place of CH-1, with the drilling of CH-1 deferred. The revised implementation schedule plans to drill the NT-C first, followed by the drilling of CH-1.

It was also confirmed at the meeting that the Ntorya to Madimba pipeline will be completed in time to receive first gas from the Ntorya field in December 2026.

APT confirmed to the parties that it had all necessary funds to carry out the revised programme for the development of the Ntorya field.

The parties agreed that APT should execute the planned activities in accordance with the revised implementation schedule and without unnecessary delay. The revised programme will now be progressed through the formal Joint Venture approval process in accordance with the Joint Operating Agreement.

Economic impact of the project

Charles Santos, executive chairman of Aminex, said, "I would like to thank Dr James Mataragio, Permanent Secretary for Petroleum at the Ministry of Energy, for convening the meeting last week and for the constructive approach taken by all parties. Our focus now is on working together to implement the agreed programme and deliver first gas without further delay.

"The revised implementation programme establishes clear near-term operational milestones, targets first gas for December 2026 and provides for the drilling of a newly planned well, NT-Central, while ensuring that the CH-1 well is also drilled.

"Together, these activities form just the beginning of the development of the giant Ntorya field which is expected to deliver large volumes of gas supplies to Tanzanians, helping alleviate energy poverty, boost industrial development and fuel Tanzania's economic growth."

Africa’s refining landscape is diverging.

Downstream

Africa’s refining landscape is entering one of its most consequential periods in decades

Across the continent, governments and investors are pursuing sharply different paths. While some are building new mega refineries, others are rehabilitating ageing assets, and several have shut down or abandoned refining altogether. The result is a fragmented energy security map in which a handful of states are moving toward product independence while others are becoming more vulnerable to global supply shocks.

This divergence raises a central question for Africa’s energy future: how will these refinery outcomes reshape regional product flows, commercial stability and long-term energy security?

Refinery revival model in Nigeria

No country illustrates the scale of Africa’s refining ambitions more clearly than Nigeria. After decades of dependence on imported refined products, the country is now positioned to become a regional product hub.

The Dangote effect

The Dangote Refinery -- Africa’s largest -- marks a structural shift in West Africa’s energy landscape. Designed to process hundreds of thousands of barrels per day, it has the potential to:

∙ Significantly reduce Nigeria’s import bill

∙ Stabilise domestic fuel supply

∙ Create export opportunities to Ghana, Togo, Benin, Cameroon and beyond

∙ Ease pressure on foreign exchange markets

Even partial operationalisation has already altered expectations across the region.

Port Harcourt rehabilitation

Alongside Dangote, the rehabilitation of the Port Harcourt refinery signals a renewed commitment to restoring legacy capacity. While timelines have shifted, the project remains symbolically and strategically important. If successful, it will complement Dangote by providing additional domestic supply and reducing reliance on imported products.

Strategic impact

Nigeria is moving from a position of chronic import dependence toward potential net exporter status. This shift could reshape West African product flows and strengthen regional energy security -- provided operational stability is achieved.

Incremental expansion and rehabilitation in Angola

Angola represents a quieter but equally important refinery story. As one of Africa’s major crude producers, its reliance on imported refined products has long been a structural contradiction.

Upgrading existing capacity

Angola has invested in upgrading its existing refining infrastructure to improve efficiency and expand output. These efforts aim to reduce import dependence and stabilise domestic supply.

New projects in development

The government has also advanced plans for new refining capacity, seeking to diversify its downstream sector and capture more value domestically.

Strategic impact

Angola’s incremental approach is gradually strengthening its energy security. While not transformative on the scale of Nigeria, it represents a steady move toward greater self sufficiency and reduced exposure to global price volatility.

Refineries closing in South Africa

South Africa offers a stark contrast. Once home to several major refineries, the country has seen its domestic refining capacity collapse.
Import dependency

By 2022–2023, all major crude refineries -- including Sapref, Enref and PetroSA’s Mossel Bay plant -- were shut or mothballed. The result is a country of South Africa’s economic size relying almost entirely on imported refined products.

Economic and infrastructure consequences

The impact has been significant:

∙ Aviation fuel shortages

∙ Bitumen shortages affecting construction

∙ Price volatility across petrol and diesel markets

∙ Heightened vulnerability to global shipping disruptions, including Red Sea tensions

Strategic impact

South Africa’s experience underscores the risks of losing domestic refining capacity. It highlights why refinery revival efforts elsewhere in Africa carry strategic weight.
Uganda's refinery story

Uganda provides a different kind of refinery story -- one shaped by geopolitics, financing pressures and environmental concerns.
The abandoned Lake Albert refinery

Uganda initially planned a refinery in the Lake Albert region to process its crude domestically. Despite years of negotiation, the project stalled due to:

∙ Financing challenges

∙ Investor withdrawal

- Geopolitical pressures

- Shifting commercial priorities

Pivot to the EACOP pipeline

Instead of a refinery, Uganda pivoted to the East African Crude Oil Pipeline (EACOP) through Tanzania. The pipeline is:

∙ More costly financially

- More environmentally sensitive

- Socially disruptive with displacement and resettlement challenges

- Still leaving Uganda dependent on imported refined products

Strategic impact

Uganda’s case shows how refinery failure can lead to long-term energy insecurity. It also illustrates how geopolitical and financial dynamics shape infrastructure outcomes across Africa.

Regional energy security

The combined effect of these refinery trajectories is a reshaped continental energy landscape.

West Africa

Nigeria’s refinery revival could stabilise regional product supply and reduce reliance on European imports. If successful, it may become the anchor of West Africa’s product market.

Southern Africa

South Africa’s refinery collapse has created regional vulnerability, with neighbouring states exposed to supply disruptions and price swings.

East Africa

Uganda’s pipeline strategy increases crude export potential but does not address product security. Kenya’s earlier refinery closure adds to regional import dependence.

North Africa

Countries like Egypt, Algeria and Morocco continue to upgrade and expand refining capacity, maintaining a more stable downstream environment.

Commercial, geopolitical and social implications

Commercial

∙ Domestic refining reduces import bills

∙ FX pressures ease when product imports decline

- Pricing reforms become more politically manageable

- Investment flows shift toward downstream infrastructure

Geopolitical

- International investors from the West, Middle East and China shape project outcomes

- Regional competition for product markets intensifies

- Maritime security risks influence supply chains

Social and environmental

- Refinery projects create employment and industrial development

- Pipeline projects raise displacement and environmental concerns

- Communities experience both benefits and burdens of energy infrastructure

Africa’s refining future

Africa’s refining landscape is diverging, not converging. Some states are building resilience through new or rehabilitated refineries, while others are becoming more dependent on imported products. The next decade will determine whether the continent emerges as a regional refining hub or remains vulnerable to external supply shocks.

What is clear is that refinery decisions made today will shape Africa’s energy sovereignty for decades to come.

The article has been written by Elijah Paul RukidiMpuuga, FCIArb (UK), founder and principal, Equitas Dispute Resolution Group, LLC

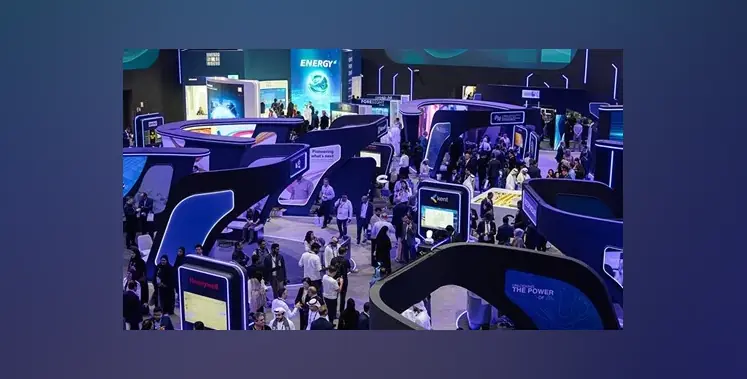
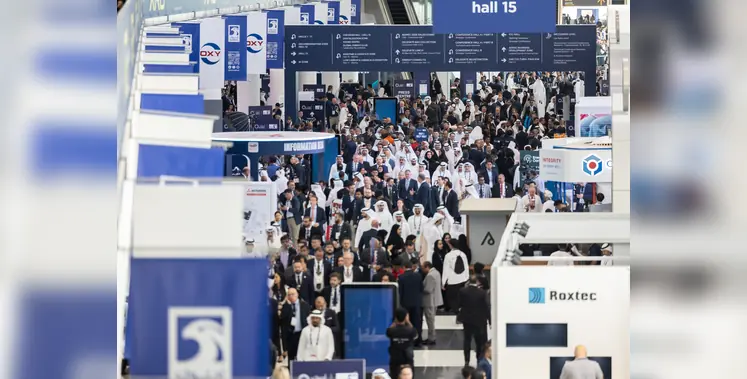
The event will convene the global energy industry in Abu Dhabi. (Image source: dmg events)

Event News

Held under the patronage of His Highness Sheikh Mohamed bin Zayed Al Nahyan, President of the UAE, in his capacity as Ruler of Abu Dhabi, ADIPEC 2026 will take place in Abu Dhabi from 2 to 5 November 2026 at ADNEC Centre Abu Dhabi

The event will mobilise investment in resilient and intelligent energy systems, with confirmed participation from ministers, CEOs and senior leaders across energy, technology, finance and industry.

The event will convene the global energy industry in Abu Dhabi as the world enters a new era of rising energy demand, geopolitical volatility, infrastructure constraints and the rapid expansion of artificial intelligence (AI), underscoring the critical importance of energy security to economic stability and growth.

As the world's largest energy conference and exhibition, and drawing on the UAE's position as a reliable energy supplier, long-term investment partner and global hub for technology and industry, ADIPEC 2026 will bring together policymakers, producers, investors, technology leaders and customers to turn shared priorities into practical action.

Across its conferences and exhibition, participants will align priorities, advance commercial partnerships and accelerate the projects and solutions needed to support secure, reliable and affordable energy supplies and long-term growth.

Among the early confirmed speakers for ADIPEC 2026 are: His Excellency Suhail Mohamed Al Mazrouei, Minister of Energy and Infrastructure, UAE; His Excellency Eng. Karim Badawi, Minister of Petroleum and Mineral Resources, Arab Republic of Egypt; His Excellency Saleh Kharabsheh, Minister of Energy and Mineral Resources, Hashemite Kingdom of Jordan; Rt. Hon Ekperikpe Ekpo, Minister for State for Petroleum Resources (Gas), Nigeria; Wael Sawan, CEO, Shell; Patrick Pouyanne, Chairman & CEO, TotalEnergies; Meg O'Neill, CEO, bp; Richard Jackson, President and CEO, Oxy; Claudio Descalzi, CEO, ENI; Christian Bruch, President and CEO, Siemens Energy; Wang Yuetao, Chairman, Zhenhua Oil; Olivier Le Peuch, CEO, SLB; Lorenzo Simonelli, Chairman and CEO, Baker Hughes; Horacio Marín, Chairman of the Board and CEO, YPF; Dr Angela Wilkinson, Secretary General and CEO, World Energy Council; Aliko Dangote, President & CEO, Dangote Group; Hunter Hunt, Chairman and CEO, Hunt Energy Holdings; Stuart Bradie, Chair of the Board, President and CEO, KBR; Dr Olivier Oullier, CEO and Co-founder, Inclusive Brains; and Prof. Haruhiko Ando, CEO, Japan Cooperation Center for Petroleum and Sustainable Energy.

Abdulmunim Al Kindy, Chairman of ADIPEC 2026, said, “Recent volatility has reaffirmed a simple truth: energy security is economic stability. As demand rises and AI transforms both the energy sector and the economies it powers, the world must invest ahead of demand, diversify supply and strengthen the infrastructure, technology and capabilities that keep energy moving.

“ADIPEC 2026 will focus on what the next energy system needs most: growth, reliability, intelligence and delivery. By bringing together policy, capital, technology and industry in Abu Dhabi, we will help advance the investments, projects and partnerships required to provide more energy, more securely and affordably, while supporting global economic growth.”

New for 2026, ADIPEC's Strategic Conference has been redesigned around the forces reshaping global energy, from rising demand and energy security to infrastructure, investment, AI, industrial execution and workforce capability.

Across 11 programmes and more than 380 sessions, ministers, CEOs, investors, policymakers and technology leaders will examine the decisions, partnerships and capital needed to expand energy supply, accelerate infrastructure delivery and strengthen long-term system performance.

New Strategic Conference programmes include Energy Security & Resilience; Policy, Regulation & Governance; Upstream; Clean Power, Molecules & Carbon Management; Grids, Infrastructure & Industrial Execution, and Workforce & Skills.

Existing programmes have also been updated to reflect the priorities shaping energy's next phase, including AI, Digital & Technology Innovation and Downstream, Chemicals & Industrial Value Chains.

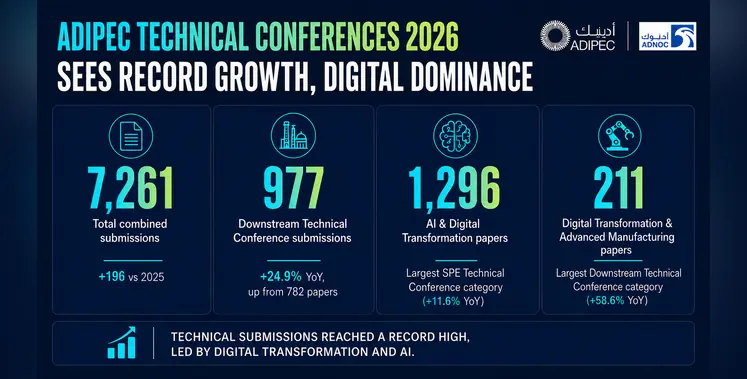
The 11 Strategic Conference programmes are complemented by the Technical Conference, with its SPE Technical and Downstream Technical programmes, which together represent the world's largest gathering of technical energy engineers and experts to transform strategy into operational delivery.

Christopher Hudson, President, dmg events (organisers of ADIPEC), said, “As the global energy landscape continues to evolve, ADIPEC's role as a platform for dialogue, collaboration and commercial engagement has never been more important. Rising energy demand, supply constraints and rapid technological advancement underscore the need to bring industry leaders together to align priorities, mobilise investment and accelerate the projects and technologies required to support long-term energy security and economic growth.

“The strong early momentum behind ADIPEC 2026 reflects the industry's recognition of both the scale of the opportunity and the urgency for action. By convening policymakers, investors, technology leaders and energy producers in Abu Dhabi, ADIPEC will help strengthen partnerships, advance innovation and support the delivery of the secure, reliable and affordable energy systems the world needs.”

The ADIPEC Exhibition will serve as a global marketplace where connections translate into commercial outcomes. In 2025, the event generated US$53 billion in value through more than 49,000 deals, demonstrating its role in advancing investment, partnerships and project delivery.

With more than 2,250 companies already confirmed to participate – including 54 NOCs, IOCs, NECs and IECs – across 16 halls and 30 country pavilions, ADIPEC 2026 is set to be one of the most influential gatherings in the global energy industry, bringing together the technologies, collaboration and investment opportunities shaping the future of energy. Four specialised zones will connect market-ready technologies and solutions with customers, investors and partners, helping move projects from opportunity to execution.