

South African dealers pairing pumps with community oasis, finds KIPX
Automotive products and commercial fuels are seeing a shift in selling approach.
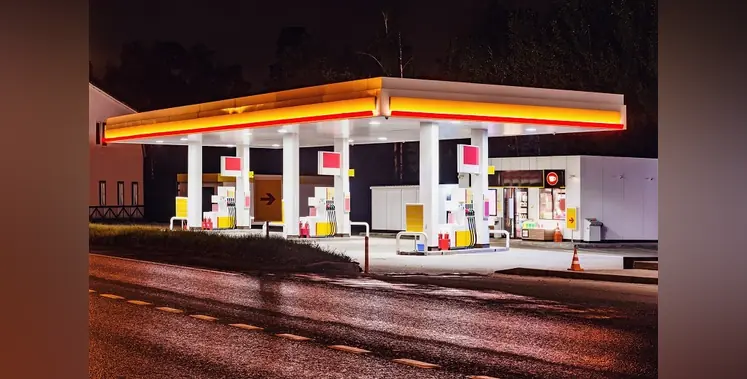
Drive into any South African town after dark and the brightest landmark on the horizon is rarely the town hall or the high street bank; it is the local fuel forecourt
Under a floodlit canopy backed by generator power and 24-hour security, commuters queue for barista coffee and fresh bread, families collect parcels from smart lockers, neighbours use the ATM, and music drifts across the tarmac from a busy car wash and grill.
In South Africa's regulated market, every station sells petrol at the same gazetted price and earns the same fixed retail margin of R3.20 per litre. Once bank card fees take 14% of that margin off the top, and before a dealer pays pump attendants, security guards, or generator diesel, fuel alone barely keeps the lights on. Because no station can compete on petrol price; what it takes to win across the country's 4,800 forecourts has changed. Nearly half of the visitors walking onto a South African forecourt today do not buy fuel. Winning now means owning the neighbourhood oasis.
The multinationals ranked: From biggest to smallest
Over the past three years, coastal refinery closures and multinational exits have redrawn the ownership map above the canopy. Ranked from largest to smallest across South Africa's branded retail network, a clear hierarchy has emerged as global commodity traders, Middle Eastern oil companies and legacy multinationals battle for the motorist.
- First is Vitol-backed Vivo Energy, commanding 27% of branded stations as the country's largest retail network.
- Second is Glencore-backed Astron Energy at 18%, having completed the nationwide rebrand of the former Caltex estate. What separates these two commodity-backed leaders is execution: Vivo Energy is scaling supermarket, bakery, and barista partnerships across urban and township nodes, while Astron Energy has used its rebrand and coastal supply integration to lock in highway and commercial corridor volumes.
- Third is Shell at 13% of branded stations, entering a new chapter as incoming Middle Eastern giant ADNOC Distribution brings sovereign capital aimed at convenience retail expansion.
- Fourth is French multinational TotalEnergies at 12%, holding a disciplined footprint across metropolitan arteries and farming hubs.
- Fifth is British major bp at 11%, whose long-term retail capital appetite faces growing market questions following its earlier exit from local refining and terminal assets.
- Sixth is domestic synfuels champion Sasol at 9%, punching above its station count after expanding its convenience footprint by a fifth in a single year.
Pressing all six from below are international challengers like Puma Energy alongside roughly 700 unbranded white-pump stations, representing around 15% of all forecourts nationwide. Supplied directly from coastal import terminals by independent wholesale traders, white-pump operators strip out multinational franchise royalties to win volume on price-sensitive rural and secondary routes.
Inside the network: Five tiers from largest to smallest
Yet the badge on the canopy tells only half the story. To see what separates winning stations from those closing their doors, KIPX audited over a thousand forecourts across a leading national network spanning nearly 700 towns.
Ranked from biggest to smallest, the network breaks into five operational tiers.
- First are flagship premium convenience hubs at 30% of the network, built as 24-hour destinations with branded supermarkets, bakeries, and drive-thru coffee.
- Second are modernised mid-tier convenience stores at 27%, serving everyday neighbourhood top-up shopping and quick-service food.
- Third are branded fuel-only canopies at 22%, pumping branded fuel without a corporate convenience store.
- Fourth are legacy and unbranded white sites at 14%, older stations that missed out on modern upgrades.
- Fifth are highway oasis complexes and standard sites, making up the remaining 7%.
Behind that ranking sits KIPX's central claim: property tenure decides who wins. Over 80% of the flagship and modernised convenience stores in the top two tiers sit on land owned or head-leased by the oil company. By contrast, nearly 80% of the fuel-only and legacy sites in the bottom tiers sit on dealer-owned land. Crucially, that 14% legacy tier accounts for 73% of all permanently closed stations. Because 94% of South African stations are run by single-site entrepreneurs, the rule is stark: where the multinational controls the title deed, it invests millions in a food-anchored oasis. Where the independent dealer owns the ground, corporate capital rarely arrives.
Where the battle is won: Suburbs, rural towns and townships
Conventional wisdom assumes convenience retail is purely an affluent suburban game. KIPX demographic mapping disproves that claim. Ranked from largest to smallest, metropolitan suburbs hold 48% of stations, rural and farming towns hold 35%, and townships hold 17%. More than half of the market sits outside suburban malls.
In metro suburbs, over two-thirds of stations have converted into flagship or modernised convenience hubs. In rural towns, the network splits in half, with upgraded stations acting as town lifelines for backup power, banking and fresh food. Townships are the fastest-growing battleground in South African retail: nearly half of township stations have been rebuilt into modern convenience oases, turning a floodlit, security-patrolled forecourt into the safest town square in the community.
Winning on the apron while lubricants move to the field
This shift has rewired how automotive products and commercial fuels are sold. Inside corporate convenience stores, old service bays were bricked up for bakeries and coffee bars because prepared food and coffee generate 44% of shop gross profit, whereas bottled motor oil has collapsed to 4% of turnover. Motorists stopped paying convenience-store markups for a five-litre jug of oil.
Instead, on the dealer-owned fuel-only and legacy stations without a corporate store, winning entrepreneurs built their own oasis on the apron. Smart dealers pair their pumps with hand car washes, shisanyama grills, sit-down kitchens and attached motor spares shops selling engine oil, filters, and brake pads at trade prices.
Meanwhile, commercial lubricant and bulk diesel volumes left the retail forecourt altogether. Multinationals, independent blenders and agile distributors now put technical reps on the road, delivering mobile diesel bowsers, 210-litre bulk packs, and 1,000-litre bulk containers straight into transport yards, farms, and mines on 30-day trade credit. Winning in South Africa's downstream market now requires mastering two distinct games: turning the retail forecourt into a 24-hour community oasis, while winning commercial fuel and lubricants in the customer's yard.